Overshoot Economics: Why GHG Verification and Adaptation Planning Are Becoming Commercial Infrastructure
- Aug, 07, 2026
The global 1.5°C carbon budget is no longer a future risk to plan around. For CBAM-exposed exporters, giga-project contractors, and Aramco-tier suppliers in Saudi Arabia, verified emissions data and adaptation planning are moving from voluntary ESG signalling to conditions of market access, insurability, and creditworthiness.
2026 Is Not a Warning. It Is the Baseline.
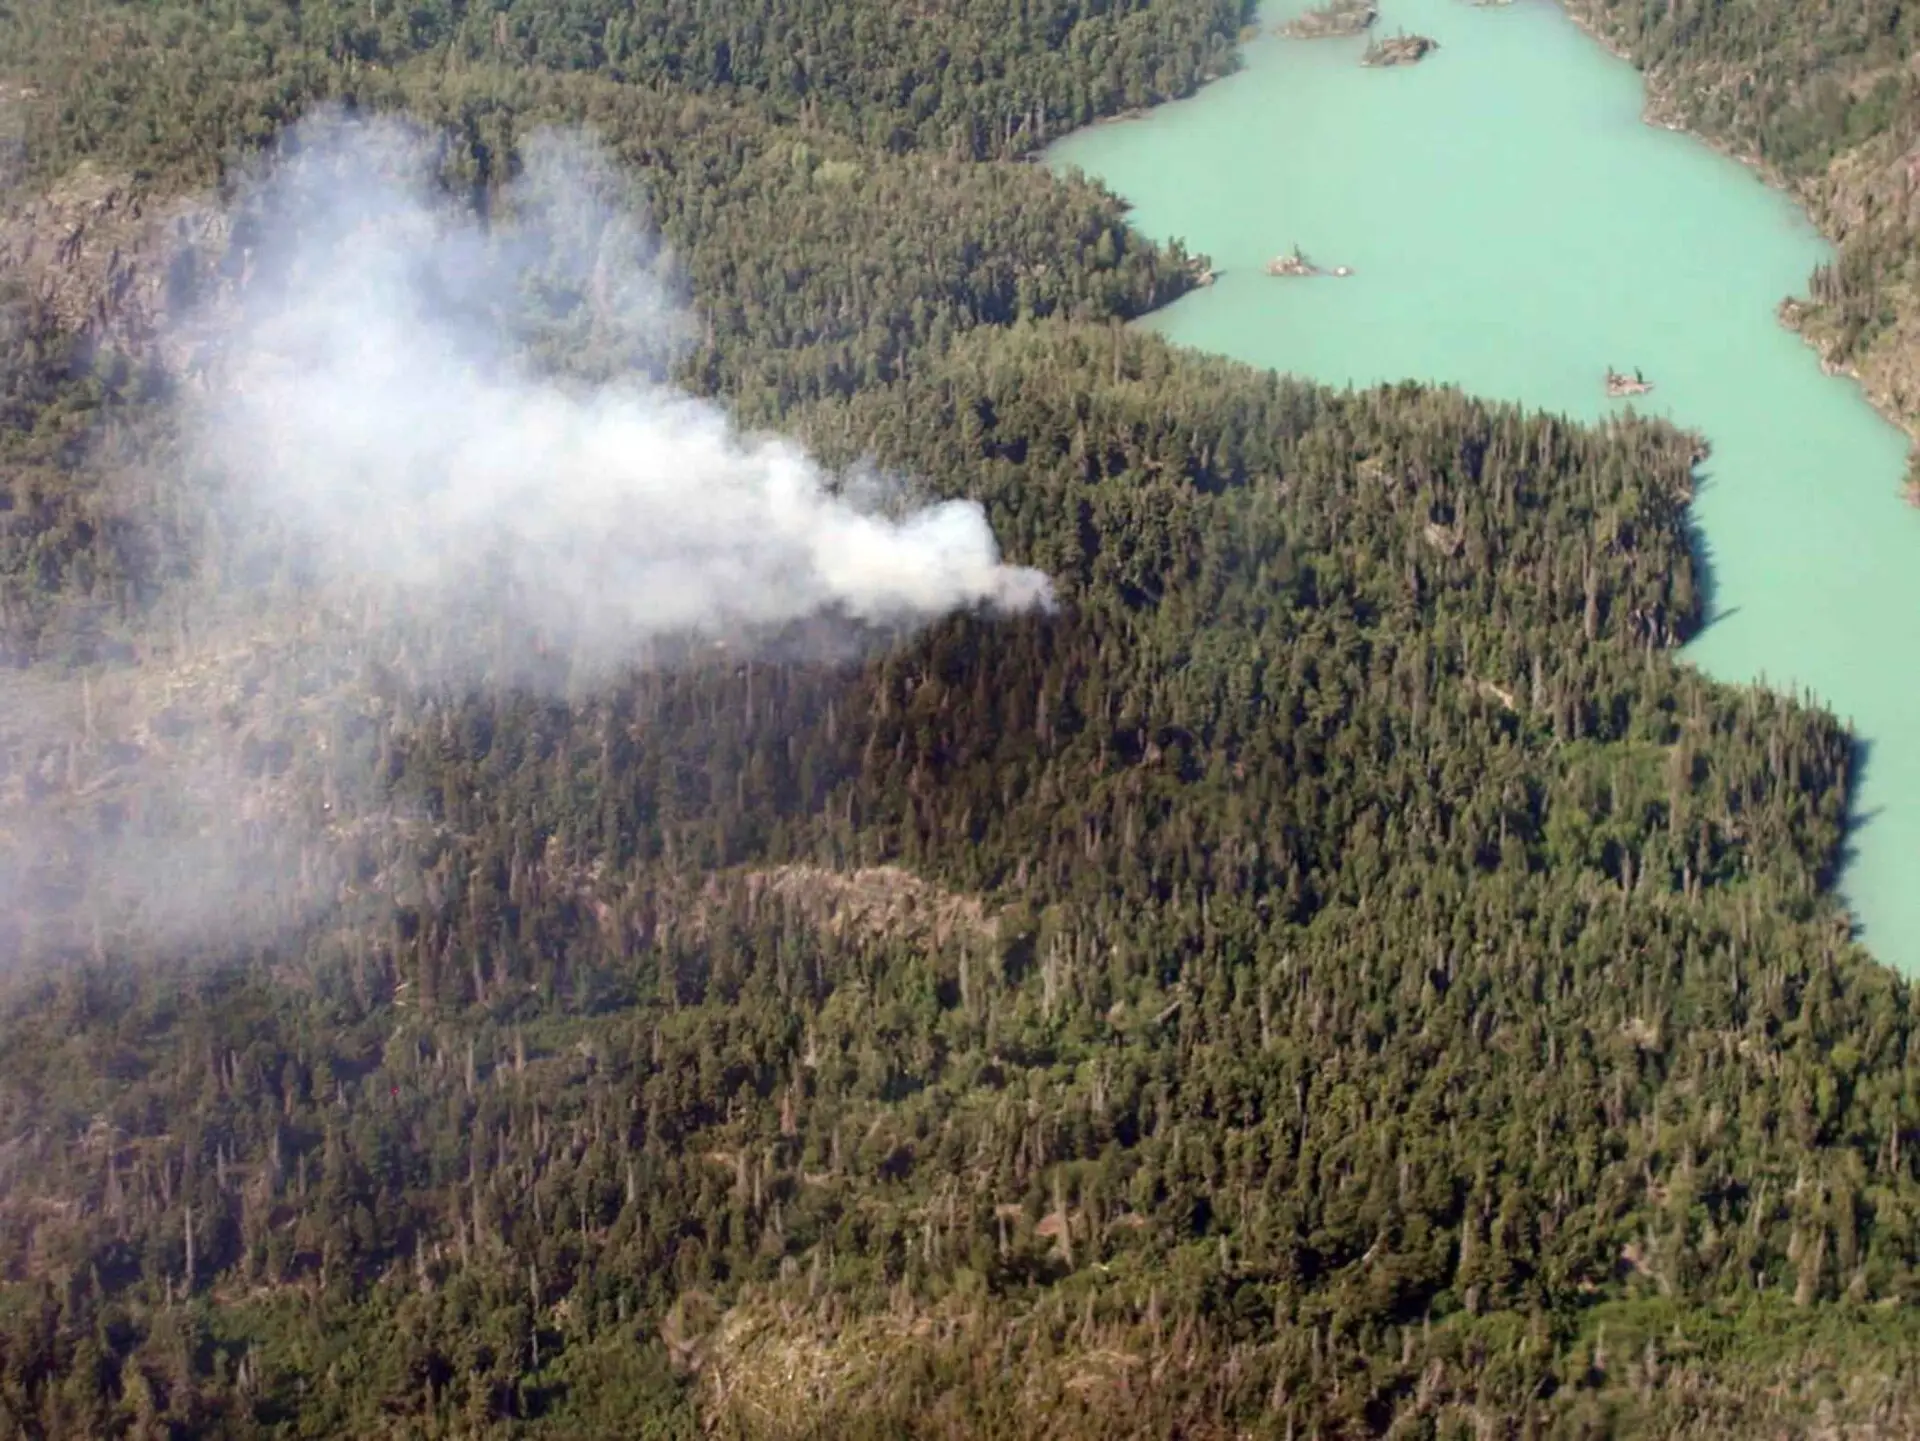
Record wildfire seasons, unprecedented heat extremes, and accelerating insurance withdrawal are not signals of a coming crisis — they are the current operating environment. This analysis sets out the data behind that shift, and the commercial logic that follows. For CBAM-exposed exporters and giga-project supply chain contractors in Saudi Arabia, this is not an abstract sustainability narrative. It is a direct input into customs liability, procurement eligibility, and long-term asset value.
The Physical and Financial Evidence, Already Visible
As of January 2026, the remaining global carbon budget stands at approximately 170 GtCO₂ for a 50% chance of holding warming to 1.5°C — roughly four years at current emission levels of ~42.2 GtCO₂ per year. Some methodologies place the 1.5°C budget as already exhausted by 2027.
Overshoot Economics: Three Defining Features
Overshoot economics describes the commercial environment that emerges once a carbon budget threshold is exceeded rather than avoided. It has three defining features relevant to CBAM-exposed exporters and Saudi giga-project contractors.
Verification becomes a market-access requirement
As overshoot accelerates, buyers, insurers, and regulators stop treating emissions data as self-reported context and start treating it as a due-diligence input with financial consequence. CBAM already prices this directly at the EU border. The direction of travel from Saudi giga-project main contractors, Aramco supplier qualification, and EU/UK trade counterparties is toward third-party-verified data as a baseline condition of doing business.
Adaptation planning becomes a proxy for institutional credibility
As physical risk repricing accelerates in insurance and capital markets, counterparties increasingly use the presence — or absence — of a credible adaptation and climate-risk plan covering heat exposure, water stress, and site-level physical risk as a signal of overall management quality. This is already visible in how reinsurers price wildfire- and heat-exposed assets, and it is migrating into supply chain qualification criteria for large contractors.
The cost of inaction compounds — it does not stay flat
Land and ocean carbon sinks show measurable degradation under heat and fire stress. 2023’s extreme heat drove a 1.73 GtC gross carbon loss from land ecosystems, with the Amazon and Canadian boreal forest both flipping toward net sources during drought and fire years. The effective remaining carbon budget is shrinking faster than official trajectories imply, and the cost of delayed compliance rises accordingly.
What This Means for CBAM Exporters and Giga-Project Contractors
CBAM-exposed exporters
CBAM’s definitive regime prices embedded emissions at the EU border using verified data — unverified or estimated defaults are penalised financially. Early, audit-ready GHG verification aligned with ISO 14064-1/3 converts a compliance cost into a pricing advantage against competitors still relying on conservative EU default values. As overshoot conditions intensify, CBAM’s sector scope and the scrutiny applied to default emissions factors should be expected to tighten.
Giga-project supply chain contractors
Contractor qualification across NEOM, Red Sea Global, Qiddiya, and Diriyah Gate is moving toward requiring demonstrable environmental management systems, not just policy statements. GHG inventories, EIA/NCEC permit compliance, and site-level physical risk planning for heat, dust, and water are becoming pre-qualification criteria rather than post-award add-ons. Contractors able to present verified emissions data and a documented adaptation plan gain a structural edge.
Positioned for This Environment
VerdeVista Consulting is built to convert overshoot-economics pressure into commercial readiness across the exact services this analysis describes — audit-defensible, ISO-aligned, and built for CBAM-exposed exporters and giga-project supply chains across Saudi Arabia and the GCC.
ISO 14064 Third-Party Verification
Provides the audit-defensible emissions data that CBAM, Aramco qualification, and buyer due diligence increasingly require as a condition of market access.
EIA / NCEC Permit Consulting
Keeps giga-project contractors ahead of tightening enforcement as regulators use permit compliance as the primary commercial lever.
Dust Monitoring & Management Planning
Converts a worsening physical-risk factor — heat, drought, dust — into a documented, defensible operational control relevant to labour safety and NCEC standing.
ESG Reporting & GRI Assurance
Builds the disclosure credibility that lenders, insurers, and TADAWUL-track investors are beginning to price into capital cost.
Energy Management (ISO 50001)
Reduces exposure to energy cost volatility that intensifies as overshoot conditions strain regional grids and water-energy systems.
“Verified emissions data and adaptation planning are moving from voluntary ESG signalling to conditions of market access, insurability, and creditworthiness.”VerdeVista Consulting · Overshoot Economics Briefing · 2026
Overshoot Is Not a Forecast. It Is Underwriting Practice.
The wildfire seasons, heat extremes, and insurance repricing documented in this analysis are not projections for the 2030s. They are 2026’s baseline. For CBAM-exposed exporters and Saudi giga-project contractors, the practical question has already shifted from whether verified emissions data and adaptation planning will be required, to how early an organisation moves before that requirement becomes a catch-up exercise rather than a competitive advantage.
This analysis is provided for general informational purposes and does not constitute a certification, verification opinion, or regulatory determination. VerdeVista Consulting maintains impartiality in accordance with ISO/IEC 17021-1 across all advisory and verification engagements.
Request a consultation
VerdeVista supports CBAM-exposed exporters and giga-project contractors across Saudi Arabia and the GCC — from ISO 14064 verification and CBAM compliance through to adaptation planning and ESG disclosure.
Book a scoping call